
Understanding the Debt Snowball Method
The Debt Snowball Method is a popular debt repayment strategy that focuses on paying off your smallest debts first while making minimum payments on larger debts. The idea is simple: by eliminating smaller debts quickly, you gain momentum and motivation to tackle larger ones. This method not only provides psychological benefits but can also help you organize your debt repayment in a manageable way.
How the Debt Snowball Method Works
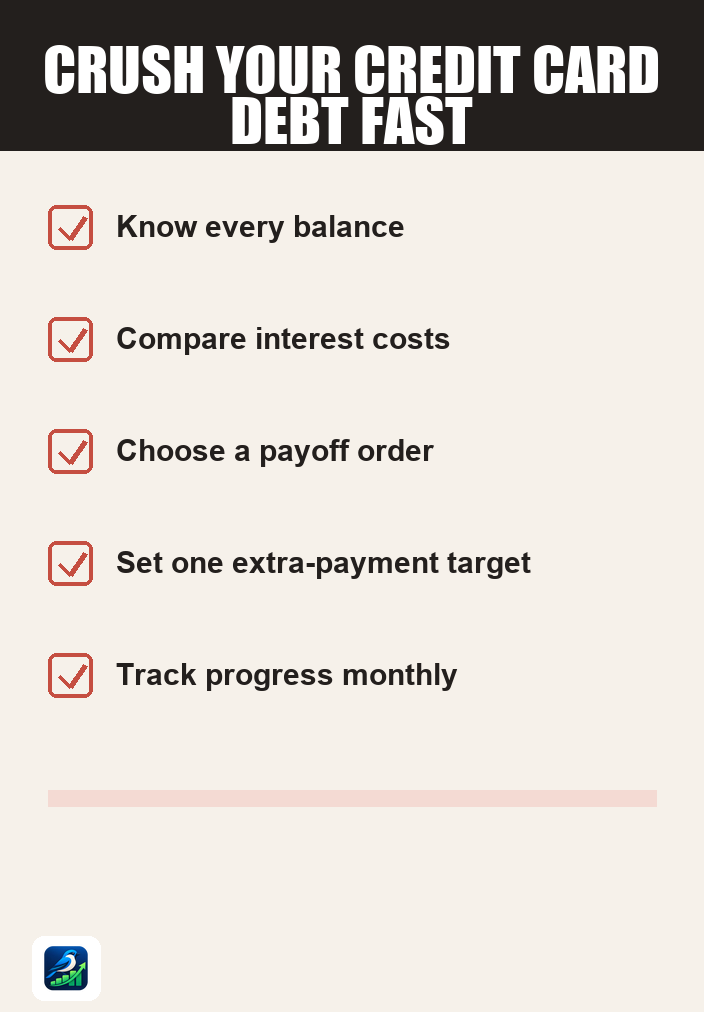
To implement the Debt Snowball Method, follow these basic steps:
- List Your Debts: Write down all your debts, including the creditor, total amount owed, interest rate, and minimum monthly payment for each.
- Order Your Debts: Arrange your debts from smallest to largest based on the total amount owed, regardless of interest rates.
- Focus on the Smallest Debt: Allocate any extra money you have each month to pay off the smallest debt while making minimum payments on the others.
- Celebrate Small Wins: Once the smallest debt is paid off, celebrate the achievement and then move on to the next smallest debt, applying the same strategy.
Example of the Debt Snowball Method
Let’s say you have the following debts:
- Credit Card A: $300 balance, $25 minimum payment
- Credit Card B: $1,200 balance, $50 minimum payment
- Personal Loan: $5,000 balance, $150 minimum payment
Following the Debt Snowball Method:
- Focus on Credit Card A first. If you have an extra $100 this month, you would pay $125 total towards this debt.
- Once Credit Card A is paid off, apply that $125 to Credit Card B’s payment, making it $175 per month.
- Continue this pattern of applying payments to the next smallest debt until all debts are settled.
Benefits of the Debt Snowball Method
The Debt Snowball Method offers several advantages:
- Motivation: Paying off smaller debts quickly can motivate you to keep going, as you see tangible results.
- Focus: This method helps you concentrate your efforts on one debt at a time, which can reduce feelings of being overwhelmed.
- Simplicity: The process is straightforward and easy to follow, making it accessible for many people.
Considerations and Trade-offs
While the Debt Snowball Method has its benefits, it’s important to consider some potential drawbacks:
- Interest Costs: This method does not take interest rates into account. If your largest debts have higher interest rates, you may end up paying more in interest over time compared to other repayment strategies, like the Debt Avalanche Method.
- Time Commitment: Depending on your financial situation, this method can take longer to pay off larger debts.
Alternatives to the Debt Snowball Method
There are other strategies for managing debt that may suit different situations:
- Debt Avalanche Method: Focus on paying off debts with the highest interest rates first. This can save you money on interest in the long run.
- Debt Consolidation: Combine multiple debts into one loan with a potentially lower interest rate. This can simplify payments but may have fees and risks.
- Debt Settlement: Negotiate with creditors to pay a reduced amount. This can be risky and may impact your credit score.
- Bankruptcy: A legal option for severe debt situations, but it has long-term consequences and should be considered only as a last resort.
Getting Started with Your Debt Snowball Plan
Ready to implement the Debt Snowball Method? Here are some practical next steps:
- Assess Your Financial Situation: Gather all necessary information about your debts and create a budget to understand your cash flow.
- Create Your Debt List: Write down your debts from smallest to largest and determine how much extra money you can allocate towards payments.
- Set Up a Payment Plan: Decide on a timeline for your repayment and stick to it, tracking your progress regularly.
- Stay Motivated: Celebrate small victories as you pay off debts, and consider joining a support group or online community for accountability.
Remember, while the Debt Snowball Method can be effective, it’s essential to find a repayment strategy that fits your personal financial situation. Evaluate all your options, and don’t hesitate to seek professional guidance if needed.



















