
Understanding Debt Relief Options
When facing overwhelming debt, it’s crucial to assess your situation carefully to determine the best path forward. Various debt relief options exist, each with unique advantages, disadvantages, and eligibility criteria. In this article, we will explore these options in depth, enabling you to make an informed decision tailored to your financial circumstances.
Debt Consolidation: Simplifying Your Payments
Debt consolidation involves combining multiple debts into a single loan, often with a lower interest rate. This process can simplify your payments and potentially lower your monthly obligations.
How Debt Consolidation Works
By taking out a new loan, you can pay off various outstanding debts like credit cards, medical bills, or personal loans. The goal is to have one monthly payment instead of multiple, which can be easier to manage.
Eligibility Criteria
- Credit Score: Generally, a higher credit score can help secure favorable loan terms.
- Debt-to-Income Ratio: Lenders will often assess your income relative to your total debt to determine your ability to repay the new loan.
- Employment Status: A stable job can boost your chances of approval.
Potential Drawbacks
While debt consolidation can be beneficial, it’s not without risks:
- Higher Interest Rates: If you have a poor credit score, you may end up with a higher interest rate than before.
- Fees: Some consolidation loans may come with additional fees, negating potential savings.
- Longer Repayment Terms: Extending the repayment period can lead to paying more interest over time.
Debt Management Plans: Structured Support
Debt management plans (DMPs) involve working with a credit counseling agency to create a structured repayment plan. The agency negotiates with your creditors to potentially lower interest rates and fees.
How DMPs Work
Once enrolled, you make a single monthly payment to the credit counseling agency, which distributes the funds to your creditors. This can simplify your financial life and reduce stress.
Eligibility Criteria
- Debt Level: Typically, DMPs are suited for individuals with unsecured debt, such as credit cards.
- Income Verification: You’ll need to demonstrate that you have a steady income to make monthly payments.
- Commitment: DMPs often require a commitment of 3 to 5 years to complete.
Potential Drawbacks
Consider the following before enrolling in a DMP:
- Fees: Some credit counseling agencies charge setup or monthly fees.
- Credit Impact: Enrolling in a DMP may impact your credit score initially.
- Restrictions: You may be required to close credit card accounts, limiting your access to credit.
Debt Settlement: Negotiating Your Debts
Debt settlement involves negotiating with creditors to pay less than what you owe. This option can be appealing if you’re struggling to make payments, but it comes with risks.
How Debt Settlement Works
You or a debt settlement company negotiate a reduced amount with your creditors. Once an agreement is reached, you pay the settled amount in a lump sum or through a structured payment plan.
Eligibility Criteria
- Debt Type: Debt settlement is generally more suitable for unsecured debt.
- Financial Hardship: You must demonstrate a financial situation that makes it difficult to repay your debts in full.
- Ability to Pay: You should have some funds available to negotiate a settlement.
Potential Drawbacks
While debt settlement may seem appealing, it’s essential to weigh the risks:
- Credit Score Impact: Settling debts can negatively affect your credit score.
- Fees: If using a settlement company, you may incur service fees.
- Tax Implications: Forgiven debt may be considered taxable income.
Bankruptcy: A Fresh Start
Bankruptcy is a legal process that allows individuals to discharge certain debts or create a repayment plan. While it can provide relief, it’s often viewed as a last resort.
How Bankruptcy Works
There are different types of bankruptcy, with Chapter 7 and Chapter 13 being the most common for individuals. Chapter 7 involves liquidating assets to pay off debts, while Chapter 13 allows for a repayment plan over three to five years.
Eligibility Criteria
- Income Level: To qualify for Chapter 7, you must pass a means test that assesses your income against the median income for your state.
- Credit Counseling: You must complete credit counseling before filing.
- Previous Filings: If you filed for bankruptcy in the past, there are waiting periods before you can file again.
Potential Drawbacks
Bankruptcy can have significant long-term consequences:
- Credit Impact: A bankruptcy filing can remain on your credit report for up to ten years.
- Asset Loss: You may have to liquidate assets to pay off creditors.
- Public Record: Bankruptcy filings are part of the public record.
Choosing the Right Option for You
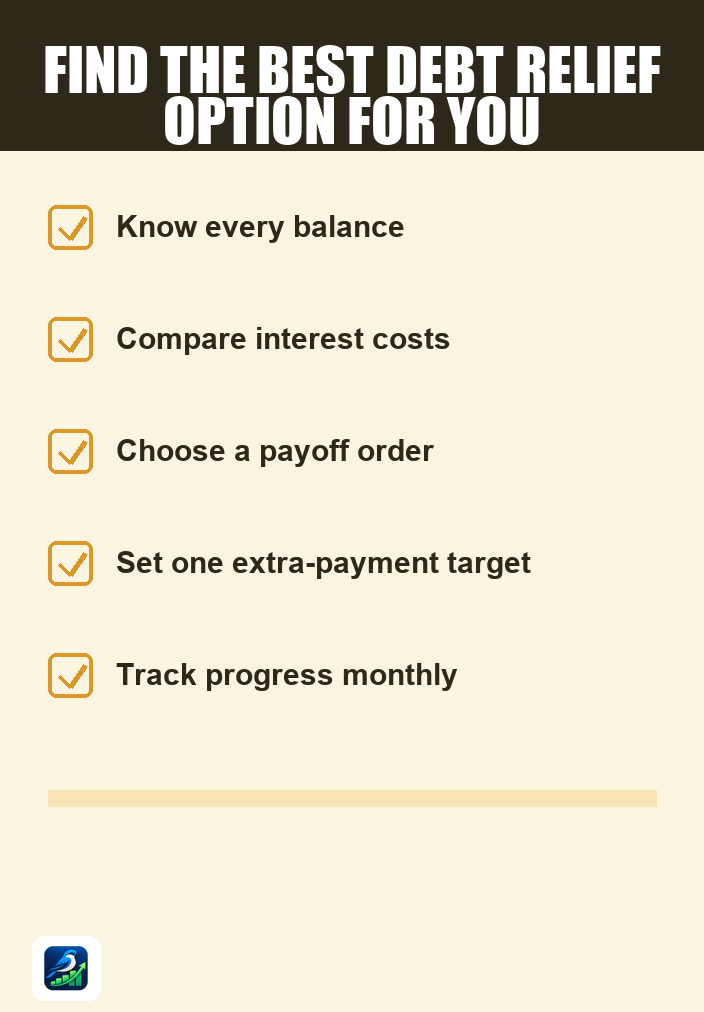
Determining which debt relief option is right for you depends on several factors, including the type and amount of debt, your financial situation, and your long-term goals. Here are some steps to help you make a decision:
1. Assess Your Debt
List all your debts, including balances, interest rates, and minimum payments. This will give you a clear view of your financial situation.
2. Evaluate Your Financial Health
Consider your income, expenses, and overall financial stability. Are you able to make minimum payments? Do you have a steady income?
3. Research Each Option
Understand the details of each debt relief method, including eligibility requirements, fees, and potential impacts on your credit.
4. Seek Professional Guidance
If you’re unsure about which option suits you best, consider consulting a financial advisor or credit counselor. They can provide personalized insights based on your situation.
Next Steps
Taking control of your debt is a significant step toward financial stability. Begin by assessing your current debt load and financial health. Research your options and consider professional guidance if necessary. Remember, the goal is to find a path that aligns with your financial situation and long-term goals.



















