
Understanding Your Debt Situation
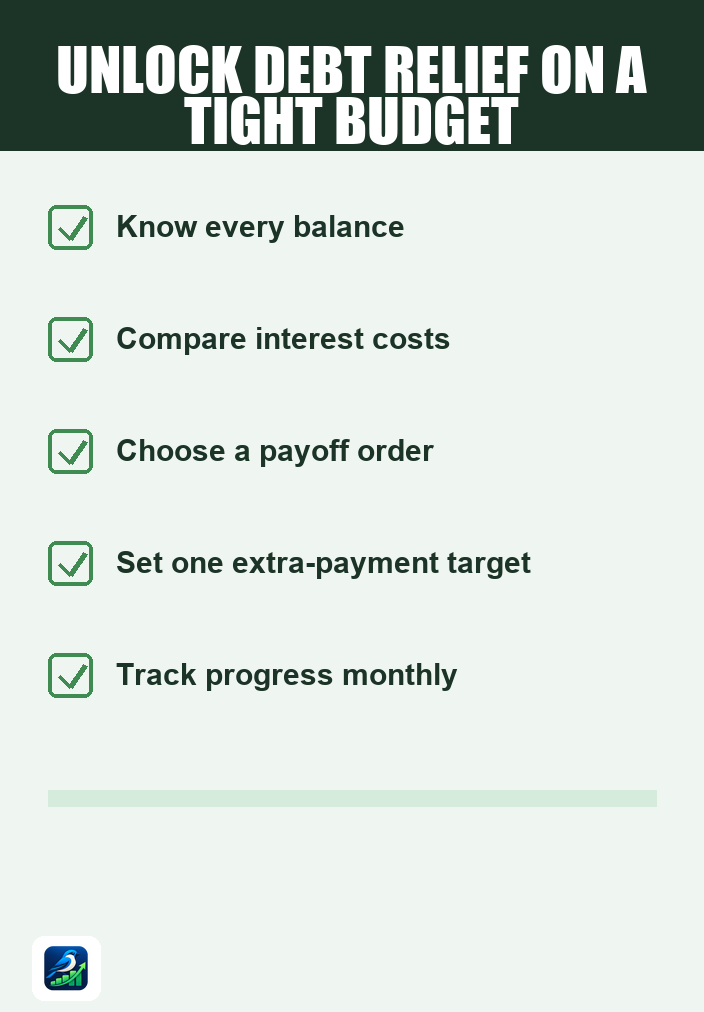
When you’re managing debt on a limited income, the first step is to gain a clear understanding of your financial situation. This includes knowing how much you owe, to whom, and the terms associated with each debt. Create a comprehensive list of your debts, including credit cards, loans, and any other obligations.
- Debt Amount: Write down the total amount owed for each debt.
- Creditor: List each creditor’s name.
- Minimum Payments: Note the minimum monthly payments required.
- Interest Rates: If applicable, include the interest rates for each debt.
By having this information organized, you can better assess your options and prioritize your payments. It’s crucial to differentiate between secured and unsecured debts, as this can affect your repayment strategy.
Creating a Realistic Budget
Once you have a clear picture of your debts, the next step is to create a budget that reflects your current income and expenses. A budget helps you understand where your money goes each month and where you can cut back to allocate more toward debt repayment.
Steps to Create Your Budget
- Track Your Income: Calculate your total monthly income, including wages, benefits, or any side jobs.
- List Fixed Expenses: Include rent, utilities, groceries, and transportation costs.
- Identify Variable Expenses: These can include dining out, entertainment, and non-essential purchases.
- Subtract Expenses from Income: Determine how much you have left over after covering your essential expenses.
With a budget in place, you may find areas where you can reduce spending, freeing up additional funds for debt repayment. Consider implementing the 50/30/20 rule as a guideline: 50% for needs, 30% for wants, and 20% for savings and debt repayment.
Debt Repayment Strategies
With a budget established, it’s time to choose a debt repayment strategy. There are two popular methods: the snowball method and the avalanche method. Each has its strengths and weaknesses, and the right choice depends on your personal preferences.
The Snowball Method
This approach focuses on paying off your smallest debts first. Once the smallest debt is cleared, you take the money you were putting toward that debt and apply it to the next smallest debt. The psychological benefit is significant; seeing debts disappear can motivate you to continue.
The Avalanche Method
Conversely, the avalanche method prioritizes debts with the highest interest rates. While this method may take longer to provide “wins,” it can save you more money on interest in the long run. Choose the method that aligns best with your motivation style.
Exploring Debt Relief Options
If your debt situation feels overwhelming, you may want to explore debt relief options. Each has different implications, so it’s essential to understand the trade-offs.
Debt Consolidation
This involves combining multiple debts into a single loan, ideally at a lower interest rate. While it can simplify payments, it may not address the underlying issues that led to debt accumulation. Be cautious, as some consolidations can extend your repayment period, resulting in more interest paid over time.
Debt Management Plans
These plans involve working with a credit counseling agency to create a structured repayment plan. While they may offer lower interest rates and waived fees, you often need to close credit accounts. Ensure you choose a reputable agency to avoid scams.
Debt Settlement
Debt settlement involves negotiating with creditors to settle debts for less than owed. While it can reduce the total amount owed, it can significantly impact your credit score and may result in tax implications. It’s not suitable for everyone and requires careful consideration.
Bankruptcy
As a last resort, bankruptcy can provide relief from overwhelming debt. However, it comes with long-term financial consequences and should not be taken lightly. Consult with a legal professional to understand your options and implications.
Taking Action
Now that you’ve assessed your situation, created a budget, and explored repayment strategies and debt relief options, it’s time to take action. Start implementing your chosen strategy and make consistent payments to stay on track.
Setting Up Reminders and Payments
Consider setting up automatic payments for your bills to avoid late fees and additional stress. Use reminders on your phone or calendar to keep track of payment deadlines and important financial tasks.
Revisiting Your Strategy Regularly
Your financial situation can change, so it’s essential to revisit your budget and debt repayment strategy regularly. Adjust your budget as needed, especially if your income increases or expenses change. Celebrate small victories to keep yourself motivated.
Next Steps
Conquering debt on a limited income is challenging, but it’s achievable with the right strategies. Start by organizing your debts and creating a realistic budget. Choose a repayment method that fits your style, explore available debt relief options, and take consistent action. Most importantly, remember that progress takes time, so be patient with yourself as you work towards financial freedom.



















