
Understanding Your Financial Situation Before Making Payments
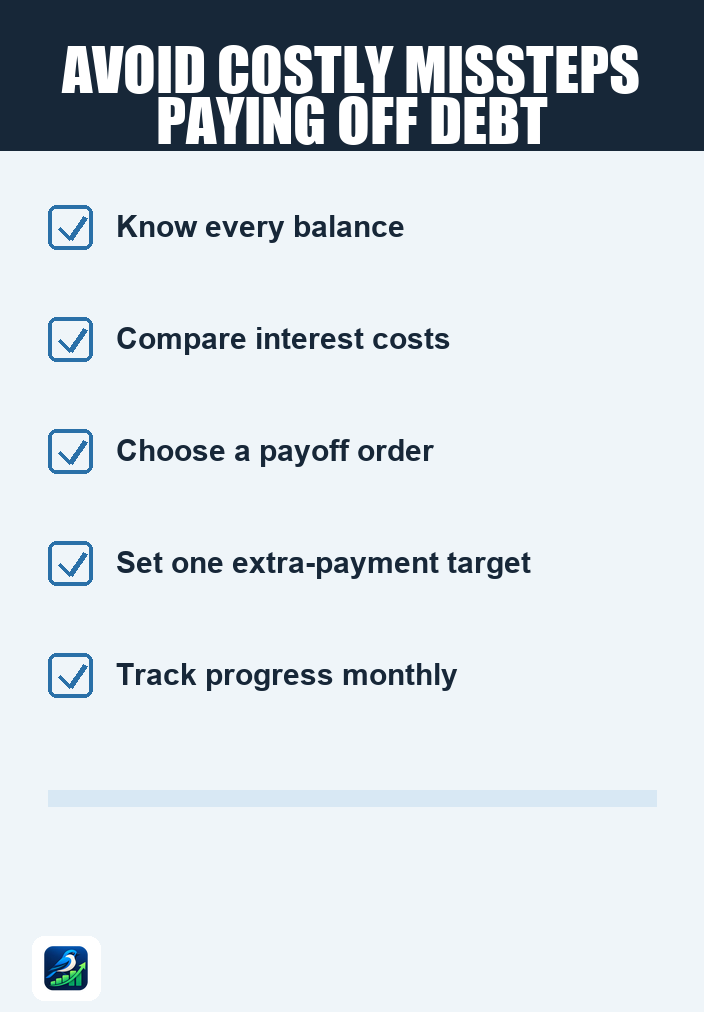
When you’re on a tight budget and trying to pay off credit card debt, the first step is to understand your financial situation clearly. This means calculating your monthly income and expenses to determine how much you can realistically allocate toward debt repayment. Without this knowledge, you might make critical mistakes that can set you back instead of helping you move forward.
Track Your Income and Expenses
Create a simple budget that outlines your income and all your necessary expenses, such as rent, utilities, groceries, and transportation. After listing your expenses, see how much you have left over each month. This will give you a clearer picture of what you can afford to pay towards your credit card bills.
Prioritize Your Debt Payments
Once you have a grasp of your finances, prioritize your debts. Focus on high-interest credit cards first, as these can cost you more in the long run. You may also want to consider whether any debts are more urgent, like those that might go to collections soon. A common method for this is the avalanche method for high-interest debt or the snowball method for paying off the smallest debts first.
Common Mistakes to Avoid
As you work on paying off your credit card debt, it’s crucial to be aware of common pitfalls that can derail your efforts.
Ignoring the Interest Rates
One of the most critical mistakes people make is ignoring the interest rates on their credit cards. If you’re only making minimum payments without taking the interest into account, you could be stuck in a cycle of debt for years. Always aim to pay more than the minimum payment when possible to reduce your principal faster.
Using New Credit Cards to Pay Off Existing Debt
Some people might consider transferring balances to new credit cards with lower interest rates as a way to manage their debt. While this can be beneficial if done wisely, it often leads to further problems if the new card is maxed out or if the introductory rate ends. Always read the fine print and have a plan for paying off the balance before the promotional period expires.
Neglecting to Communicate with Creditors
If you’re facing financial difficulties, it’s essential to communicate with your creditors. Many credit card companies offer hardship programs or can work with you to set up a more manageable payment plan. Ignoring your creditors can lead to missed payments and damage your credit score.
Not Considering Debt Consolidation or Management Plans
For some, debt consolidation or enrolling in a debt management plan can be effective ways to simplify payments and potentially lower interest rates. However, it’s crucial to understand the trade-offs. Consolidation might extend your repayment period, which can increase the total interest paid over time. Debt management plans often require you to close credit accounts, which can impact your credit utilization ratio.
Long-Term Planning and Emotional Considerations
Paying off credit card debt isn’t just a financial issue; it’s often an emotional journey as well. It’s important to approach it with a long-term mindset.
Set Realistic Goals
Setting expectations is key. Pay off your debt with small, achievable goals instead of overwhelming yourself with the total amount. For example, aim to pay off one credit card within a specific timeframe. Celebrate these small victories to keep yourself motivated.
Recognizing Emotional Triggers
Be aware of your emotional triggers that lead to overspending. It could be stress, boredom, or social pressures. Understanding these triggers can help you develop strategies to avoid unnecessary spending in the future, such as finding alternative activities or coping mechanisms.
The Role of Professional Guidance
Sometimes, you may feel overwhelmed by your debt situation. Seeking help from a financial advisor or credit counselor can provide you with tailored advice and strategies. Just be sure to choose a reputable service.
Understanding Your Options
Choosing the right form of assistance is important. Here are some common options:
- Debt Consolidation: Combining multiple debts into a single loan with a potentially lower interest rate.
- Debt Management Plans: Working with a credit counseling service to create a repayment plan that may reduce interest rates and fees.
- Debt Settlement: Negotiating with creditors to pay a lump sum that is less than the total debt owed. This can negatively impact your credit score.
- Bankruptcy: A legal process that may eliminate some debts but can have long-lasting effects on your credit history.
Each option comes with its own set of risks and benefits, so it’s essential to carefully weigh these before making a decision.
Next Steps
As you work through your credit card debt, take the time to reassess your financial situation regularly and adjust your budget as needed. Remember to communicate openly with creditors and consider seeking professional guidance if you feel stuck. Staying informed and proactive can make all the difference in your journey to financial freedom.



















