
Understanding Credit Recovery and Its Importance
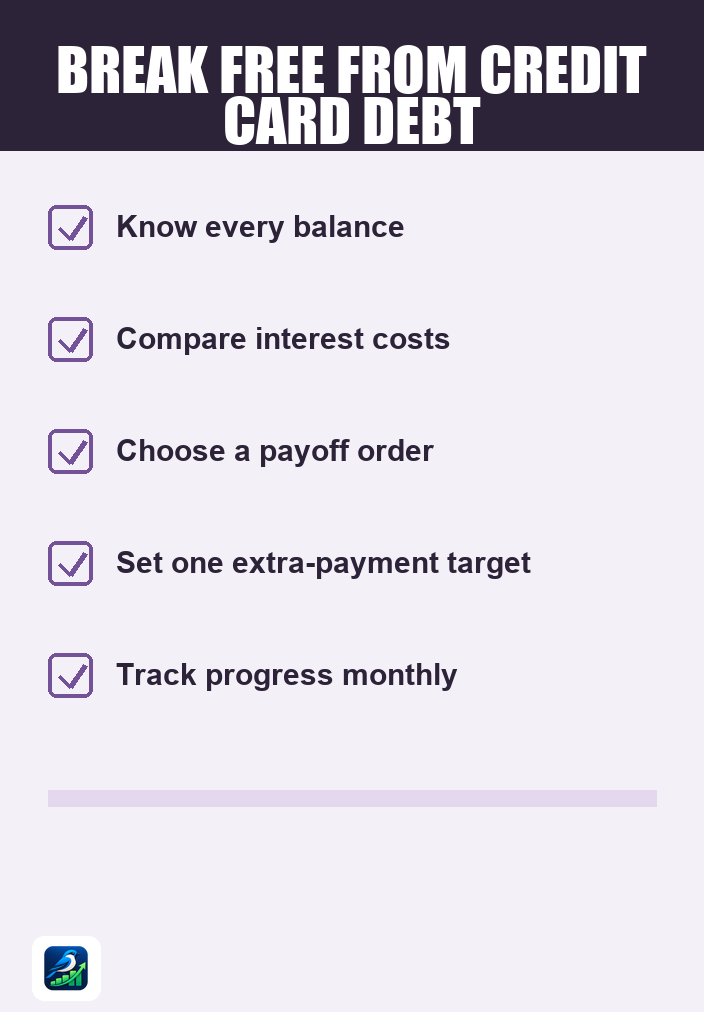
Recovering from credit issues can feel overwhelming, but developing effective credit recovery habits is essential for long-term financial health. This article outlines a comprehensive checklist to help you understand, organize, and reduce your consumer debt while improving your credit situation. By following these steps, you can create a solid foundation for a more stable financial future.
Assess Your Current Financial Situation
The first step in any credit recovery journey is to gain a clear understanding of your current financial situation. This includes taking stock of your debts, income, and expenses.
1. Create a Debt Inventory
List all your debts, including credit cards, personal loans, and any other obligations. For each debt, note the following:
- Creditor name
- Total amount owed
- Minimum monthly payment
- Interest rate (if applicable)
- Due dates
2. Analyze Your Income and Expenses
Next, evaluate your monthly income and expenses. Create a budget to track where your money is going. This will help you identify areas where you can cut back and allocate more funds towards debt repayment.
Establish a Budget and Payment Plan
With a clear picture of your financial situation, you can develop a realistic budget and payment plan. These will be key components of your credit recovery habits.
3. Set Up a Monthly Budget
Your budget should include all sources of income and list fixed and variable expenses. Aim to ensure that your expenses do not exceed your income. If they do, prioritize necessities and look for ways to reduce discretionary spending.
4. Choose a Debt Repayment Strategy
There are several strategies for paying down debt. Consider the following:
- Debt Snowball Method: Focus on paying off the smallest debt first while making minimum payments on larger debts. Once the smallest debt is cleared, move to the next smallest.
- Debt Avalanche Method: Concentrate on paying off debts with the highest interest rates first. This method could save you more money in interest over time.
Choose the method that resonates with you and fits your financial circumstances best.
Explore Debt Relief Options
If your debts feel unmanageable, there are several debt relief options to consider. Each option has its pros and cons, so it’s crucial to weigh them carefully.
5. Debt Consolidation
This involves combining multiple debts into a single loan, often with a lower interest rate. While this can simplify payments, it may extend the repayment period and could lead to accumulating more debt if not managed carefully.
6. Debt Management Plans
A debt management plan (DMP) involves working with a credit counseling agency to create a structured repayment plan. While this can help reduce interest rates and monthly payments, it often requires closing credit accounts, which could impact your credit score.
7. Debt Settlement
Debt settlement involves negotiating with creditors to pay less than the total amount owed. While this can lead to significant savings, it can also severely impact your credit score and may have tax implications.
8. Bankruptcy
Bankruptcy is a legal process that can provide relief from overwhelming debt. However, it has long-term consequences on your credit and should be considered a last resort. Consult with a legal professional to understand the implications.
Adopt Healthy Credit Habits
In addition to managing existing debt, establishing healthy credit habits is vital for long-term recovery.
9. Regularly Monitor Your Credit Report
Check your credit report regularly to understand how your actions impact your credit score. Look for errors or inaccuracies and dispute them promptly. Many credit reporting agencies offer free access to your credit report annually.
10. Make Payments on Time
Consistent, on-time payments are one of the most effective ways to improve your credit score. Set up reminders or automate payments to avoid missing due dates.
11. Avoid New Debt
While you’re working on recovery, avoid taking on new debt. This includes refraining from applying for new credit cards or loans unless absolutely necessary.
Build an Emergency Fund
Having an emergency fund can provide a safety net and prevent you from falling back into debt when unexpected expenses arise.
12. Set Savings Goals
Start by aiming to save a small amount each month. Gradually increase your savings until you have at least three to six months’ worth of living expenses set aside. This can help cushion you against unforeseen financial stressors.
Next Steps for Effective Credit Recovery
Recovering from credit issues doesn’t happen overnight. It requires commitment and ongoing effort. Here’s a simple action plan to get started:
- Assess your current financial situation by creating a debt inventory and analyzing your income and expenses.
- Establish a budget and select a debt repayment strategy that aligns with your goals.
- Explore debt relief options and understand their implications.
- Adopt healthy credit habits, including regular monitoring and timely payments.
- Start building an emergency fund to safeguard against future financial difficulties.
By following this checklist and incorporating these practices into your daily life, you can create a sustainable path towards credit recovery and financial stability. Remember, the journey may be challenging, but with determination and the right habits, you can regain control of your financial future.



















