
Understanding Your Credit Report: The Importance of Late Payments
Your credit report plays a crucial role in your financial life. It influences your ability to secure loans, rent an apartment, or even land a job. Late payments are one of the most significant factors that can negatively impact your credit score. If you’ve experienced late payments, understanding how to prepare your credit report can help you manage the effects and improve your financial standing.
Step 1: Obtain Your Credit Report
The first step in preparing your credit report is to obtain a current copy. You can typically get one free credit report annually from each of the major credit reporting agencies. Here’s how to do it:
- Visit the official website for free credit reports.
- Follow the instructions to request your report.
- Review it thoroughly for accuracy.
Pay special attention to any late payments noted in your report, as these will affect your credit score. Not all late payments are reported the same way, so understanding the details is crucial.
Step 2: Analyze Your Late Payments
Once you have your credit report, take the time to analyze the late payments. Here are some key questions to consider:
- When did the late payment occur?
- How late was the payment (30, 60, 90 days)?
- Is the late payment accurate? Or is there a chance it was reported in error?
- Was the late payment a one-time occurrence or indicative of ongoing financial trouble?
Identifying the nature and frequency of your late payments will help you develop a strategy for addressing them.
Step 3: Dispute Inaccuracies
If you find any inaccuracies regarding your late payments, it’s essential to dispute them promptly. Here’s how to do that:
- Gather supporting documentation that proves the error.
- Contact the credit reporting agency that issued the report.
- Submit a formal dispute, including your evidence.
- Keep records of all correspondence.
Disputing inaccuracies can potentially help remove erroneous late payments from your credit report, which can positively impact your credit score.
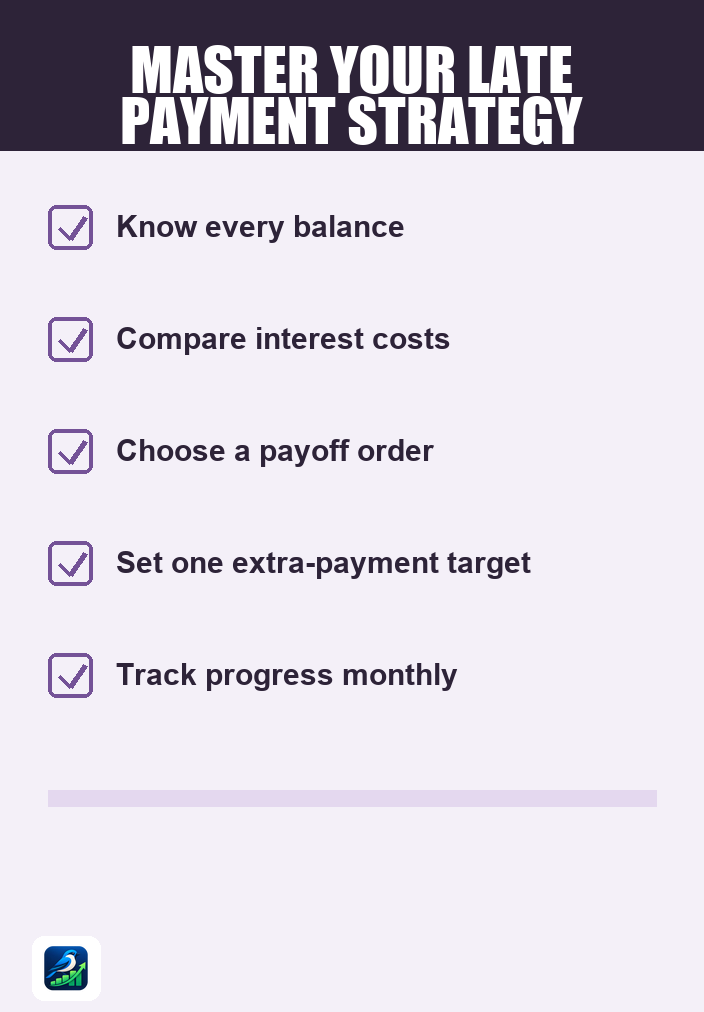
Step 4: Make a Payment Plan
If late payments are accurate, it’s time to take proactive steps. Creating a payment plan can help you catch up. Here’s how to start:
- List all debts with late payments and their outstanding amounts.
- Prioritize them based on interest rates and payment deadlines.
- Set a realistic budget to allocate funds each month toward these debts.
- Consider negotiating with creditors for payment plans or settlements, if necessary.
Making regular payments—even if they are less than the minimum—can demonstrate your commitment to addressing the debt and may mitigate some negative impacts on your credit report.
Step 5: Establish Positive Credit Habits
Once you’ve addressed existing late payments, developing positive credit habits is crucial for long-term improvement. Consider implementing these practices:
- Set up automatic payments for bills to avoid future late payments.
- Use calendar reminders for payment due dates.
- Maintain a budget that prioritizes debt repayment.
- Consider opening a secured credit card to rebuild credit responsibly.
Positive actions can gradually improve your credit score over time, helping to offset the impact of past late payments.
Step 6: Monitor Your Credit Regularly
After taking steps to improve your credit report, it’s essential to monitor your credit regularly. This can help you:
- Keep track of any changes to your credit score.
- Identify new late payments or inaccuracies quickly.
- Stay informed about your overall credit health.
Monitoring your credit report can empower you to make informed financial decisions and maintain good credit health.
Step 7: Consider Professional Help
If you find managing your late payments overwhelming, seeking professional help may be a viable option. Credit counseling services can assist you in:
- Creating a personalized debt management plan.
- Negotiating with creditors on your behalf.
- Providing education about managing finances and improving credit.
While professional help can come with fees, it may also provide you with the tools and knowledge to regain control over your finances.
Next Steps: Taking Control of Your Financial Future
Preparing your credit report and managing late payments is a crucial step in regaining financial stability. Start by obtaining your credit report, analyzing your late payments, and disputing inaccuracies. Establish a payment plan and develop positive credit habits to improve your situation over time. Regular monitoring and professional guidance can further support your efforts.
Remember, the journey to recovery and improved credit health is ongoing. Take it one step at a time, and don’t hesitate to reach out for help when needed.



















